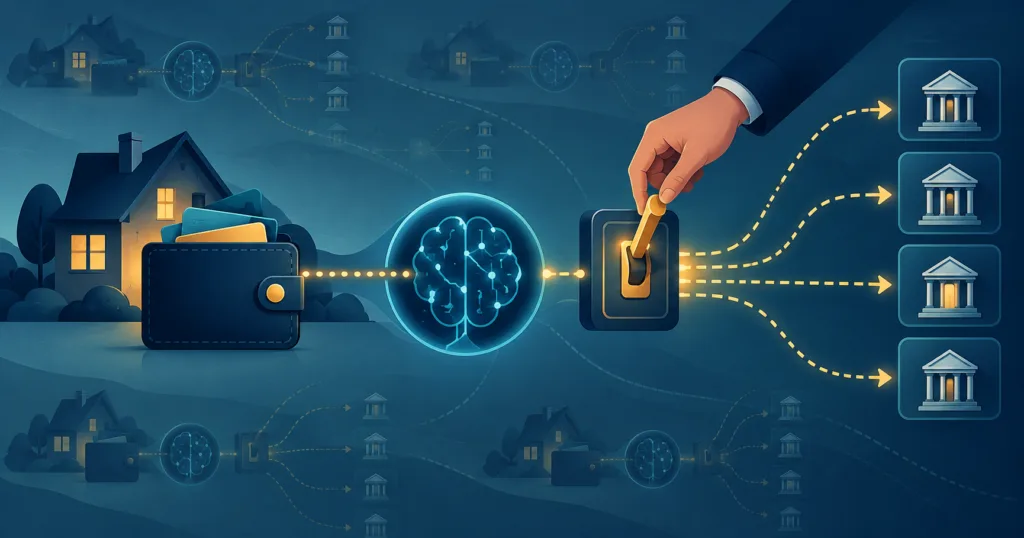
Apollo chief economist Torsten Slok sees a potential banking risk in a useful consumer service: AI assistants finding a better return on idle cash. His “agentic bank run” scenario imagines households authorizing software to move money out of low-paying accounts, potentially putting banks under pressure if those decisions happen at scale.
For an individual saver, the attraction is straightforward. A higher interest rate means more income from the same balance. For banks that depend on inexpensive deposits, widespread automated switching could make that funding harder to retain.
The key comparison involves both the return on the money and what an assistant has permission to do with it.
Low-yield balances versus higher-paying accounts
Consider a hypothetical $10,000 balance earning either 0.1% or 5% annually. Holding the balance and rate constant for a year, the difference is $490 before taxes and fees.
| Assumed annual yield | Interest after one year |
|---|---|
| 0.1% | $10 |
| 5% | $500 |
These figures illustrate the incentive to switch; they are not a comparison of live offers or a promise that a particular account will pay either rate. They assume an unchanged annual yield and no deposits or withdrawals.
Slok’s scenario hinges on AI making that comparison easier to act on. An assistant tasked with improving the return on cash could, if it had the necessary capabilities and authorization, identify a higher-paying destination and arrange a transfer. The potential benefit is less work for the customer. The banking concern is how many customers might make the same move together.
Account access and transfer authority are separate capabilities
Meta’s Muse helps explain why financial AI assistants feature in this debate. Plaid says its integration lets users connect financial accounts and share information such as balances, transactions and investment holdings with Muse. That gives the assistant financial context for personalized guidance.
Access to that information does not, by itself, establish permission or functionality to move money. A tool that can explain a balance or discuss a financial goal occupies a different role from one entrusted to transfer savings between accounts.
Muse’s account connections illustrate the guidance side of that comparison. Slok’s scenario depends on assistants also being able and authorized to initiate transfers.
Plaid says people choose whether to connect their accounts and can manage those connections through Plaid Portal. Managing access to financial data is a separate function from authorizing a transfer.
That distinction matters when comparing AI agents. The useful question is what the service can actually execute, with which permissions, and how much involvement the user retains. An account connection alone cannot answer those questions.
Why faster switching could pressure banks
Low-cost deposits can help banks fund lending. If those balances leave, an affected bank may need to offer more competitive rates or turn to more expensive funding. Either response could put pressure on the economics of its loans.
Automation could accelerate that adjustment if it reduced the effort involved in finding and acting on better rates. The scenario becomes more concerning when many assistants respond to the same incentives over a short period.
Even then, an outflow from one institution does not establish a loss of deposits across the entire banking system. Money moved to another bank changes where deposits sit. The pressure on individual institutions would depend on the size and speed of withdrawals and their capacity to meet them.
That makes “agentic bank run” a description of a possible stress scenario. A rate comparison alone cannot establish how likely it is, how large it would become or which banks would be most exposed.
The broader concern is similar decisions at scale
The Bank of England has warned that advanced AI trading strategies could encourage firms to take similar positions and respond alike during periods of stress, potentially making market shocks worse. Shared models, data or approaches could contribute to that convergence.
Former SEC chair Gary Gensler raised a related concern in 2023: reliance on a small number of AI platforms or data providers could encourage financial actors to make similar decisions.
Those warnings concern broader financial behavior. Applying them to household cash management suggests a possible parallel: assistants given similar goals and information might recommend or execute similar transfers. That remains an inference, rather than evidence that synchronized withdrawals will occur.
What matters when comparing financial assistants
The distinction between guidance and execution gives readers three practical comparison points:
- Financial visibility: Which balances, transactions or holdings can the assistant access?
- Action capability: Can it provide guidance, prepare a transfer or actually execute one?
- User control: What authorization does an action require, and which decisions remain with the account holder?
Higher returns explain the appeal of automated cash management. Transfer capability, customer permission and widespread adoption determine whether that appeal could translate into the banking pressure Slok describes.